Many Indian families and investors look at Dubai when they think about owning property abroad. The process is clear once you know the steps: foreign buyers can own property outright in Dubai’s freehold areas, and every sale is registered with the Dubai Land Department (DLD).
This guide explains how it works for Indian buyers, whether you live in India or are a non-resident Indian (NRI) in the UAE or elsewhere — from paying for the property to receiving your title deed.
Can Indians buy property in Dubai?
Yes. Foreign nationals can own property in Dubai’s designated freehold areas, while UAE and GCC citizens can own throughout the emirate, according to the Dubai Land Department (opens in a new tab). Freehold means the property is registered in your own name with DLD and you receive a title deed.
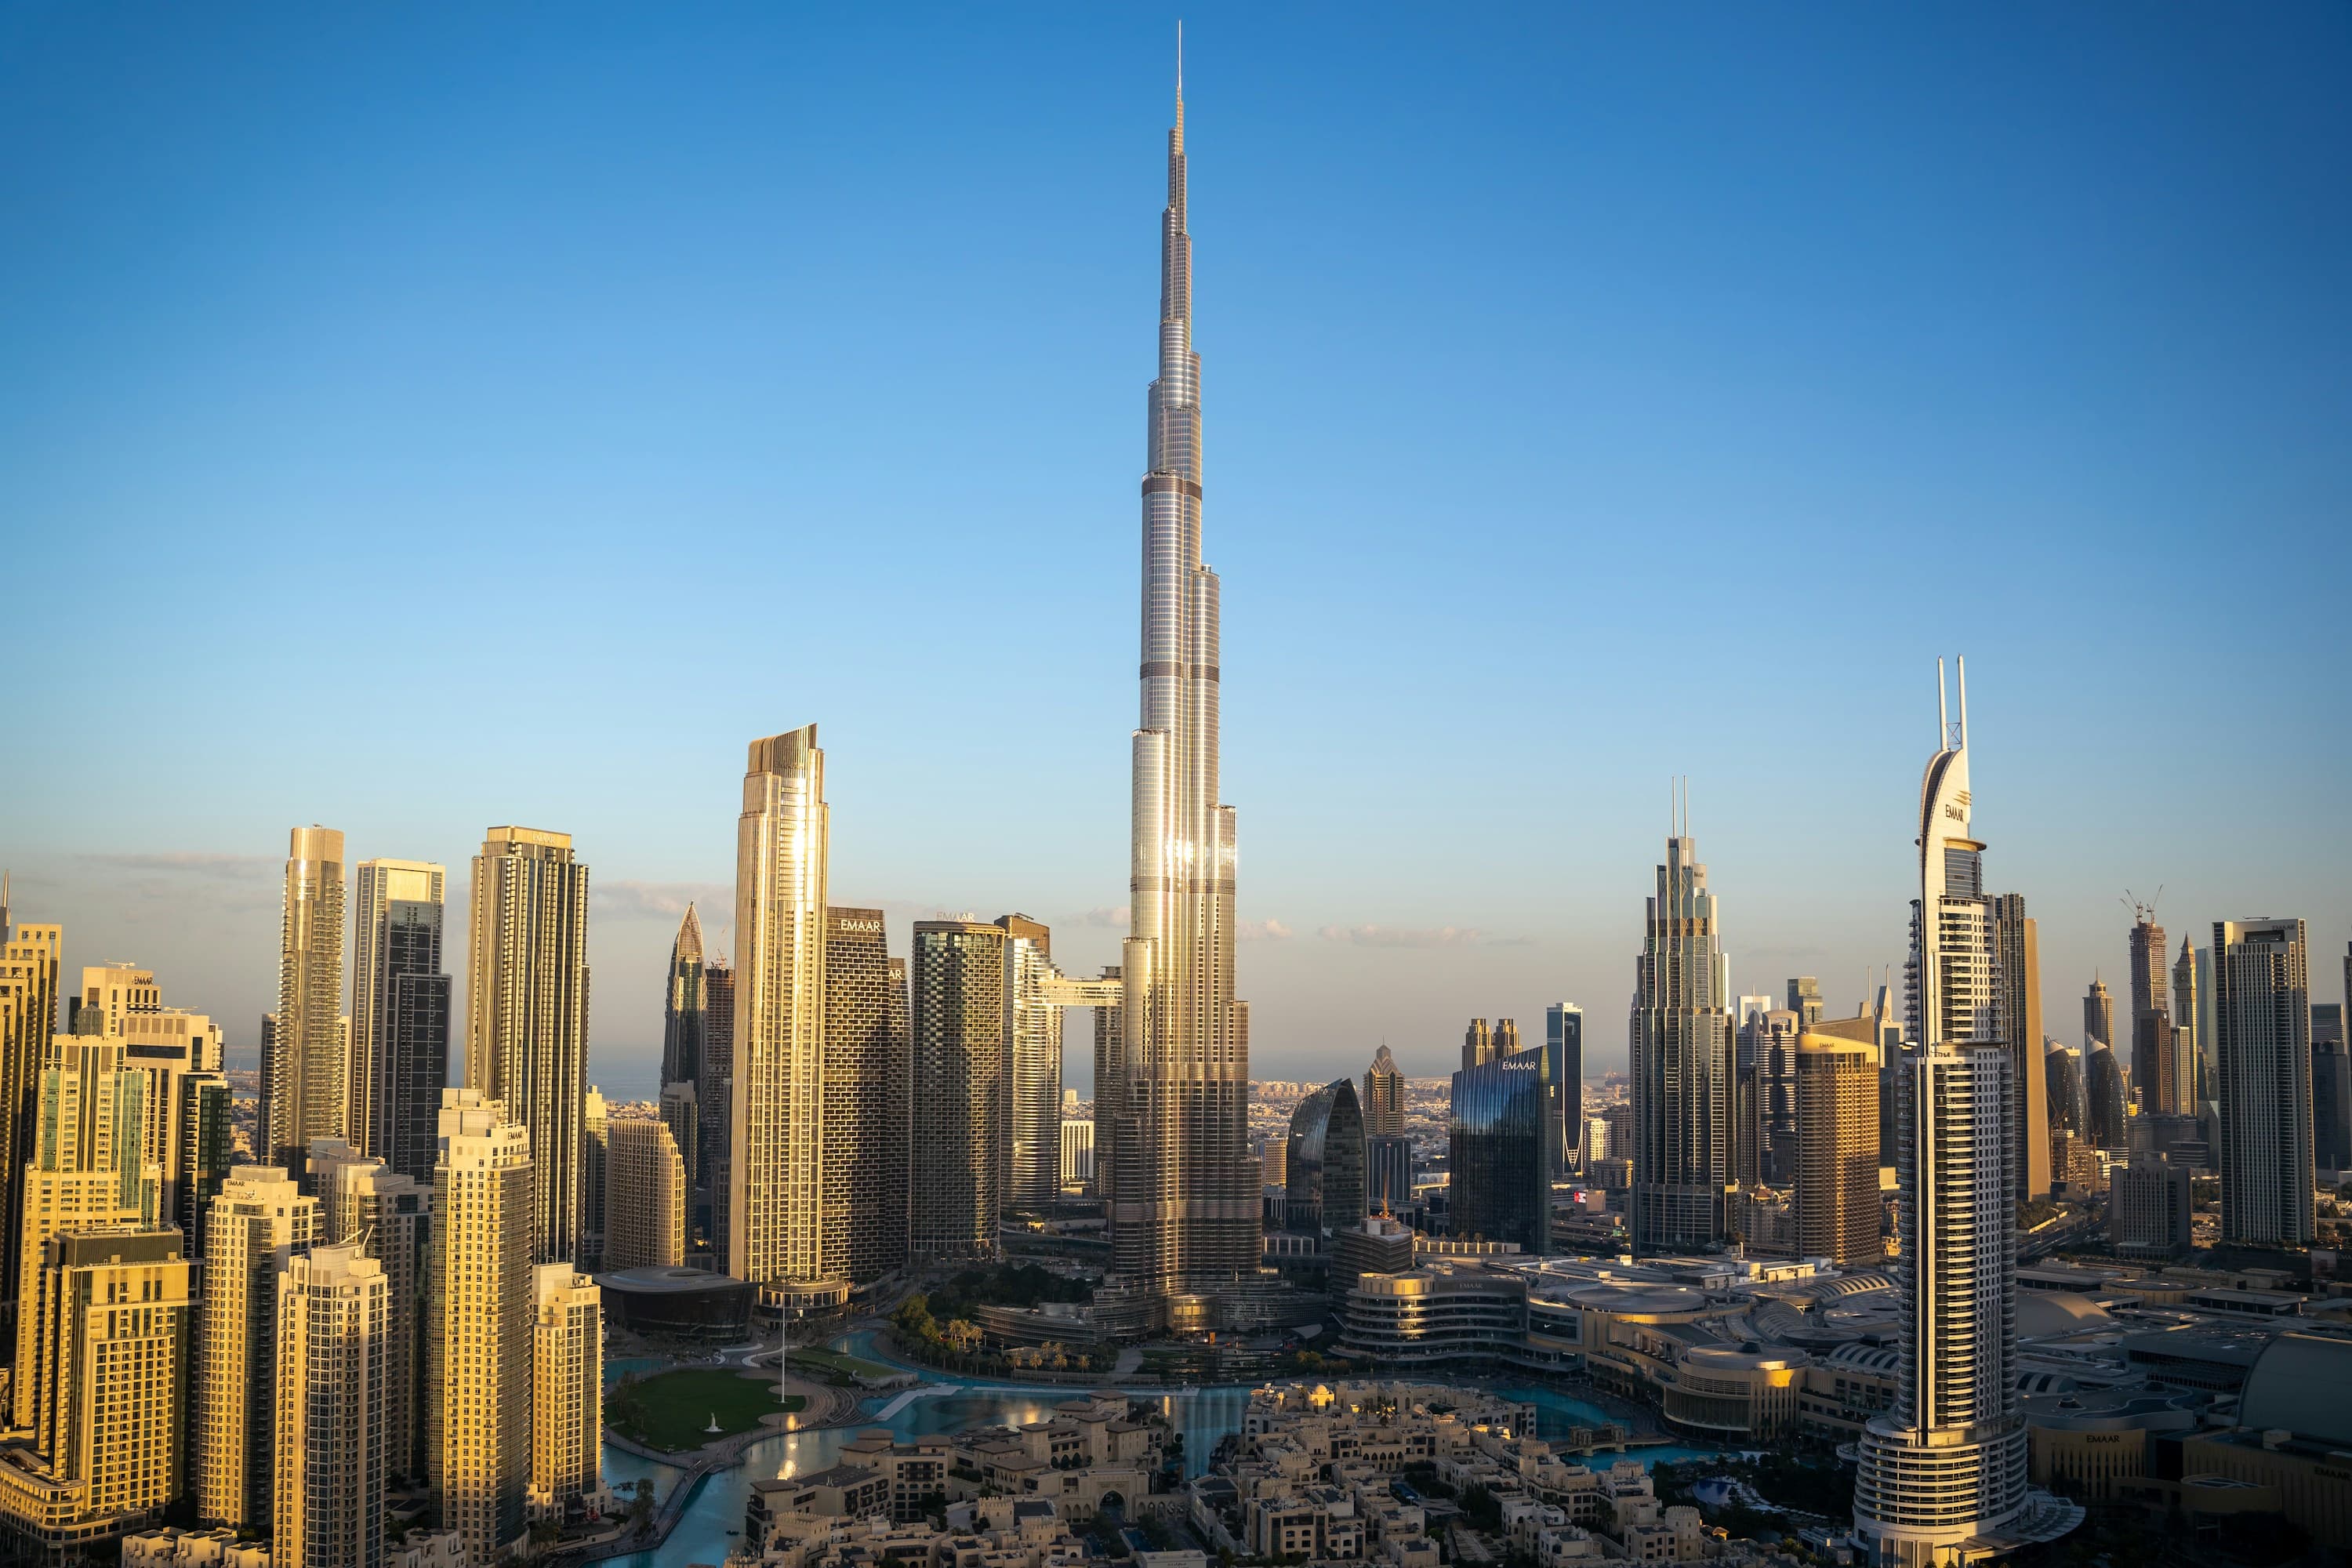
Well-known communities such as Downtown Dubai and Dubai Marina are freehold, as are many newer master-planned communities. We confirm the status of any specific property before you commit.
You don’t need to live in the UAE to buy. DLD accepts a valid passport as identification for non-resident buyers, and if you can’t be in Dubai for the transfer, a legally valid power of attorney can act for you (DLD (opens in a new tab)).
Paying for a Dubai property from India
If you live in India, the Reserve Bank of India’s Liberalised Remittance Scheme (LRS) (opens in a new tab) lets each resident individual send up to USD 250,000 per financial year (April to March), and acquiring immovable property abroad is one of the permitted purposes. The limit is shared with everything else you send under LRS that year, such as travel, gifts or education costs.
Family members can combine their limits for a property only if they are co-owners of it, according to the RBI’s LRS FAQs (opens in a new tab). Your bank handles the remittance paperwork, and tax rules such as tax collected at source (TCS) can apply to foreign remittances — so check the current position with your bank or chartered accountant before you transfer.
If you’re an NRI, LRS is a scheme for residents of India, so it doesn’t govern money you earn and hold abroad. If you plan to use funds held in India, ask your bank which accounts and rules apply to you.
Always pay by bank transfer to the account named in your contract. For an off-plan home, that’s the project’s escrow account.
Ready or off-plan?
A ready property is complete, so you can move in or rent it out soon after the transfer. An off-plan property is bought from the developer before or during construction, with payments usually spread across the build under a payment plan.
| Ready property | Off-plan property | |
|---|---|---|
| Move in or rent out | Soon after the transfer | After completion and handover |
| How you pay | The price at transfer, in cash or with a mortgage | In stages under the developer’s payment plan |
| Where your money goes | To the seller (and their bank, if the home is mortgaged) | Into the project’s escrow account |
| Registration | Transfer at a Real Estate Registration Trustee office, then a DLD title deed | Registered by the developer with DLD; title deed after completion |
Off-plan buyers are protected by Dubai’s escrow law (Law No. 8 of 2007): developers must pay buyers’ money into a separate escrow account for each project, and those funds can only be used for its construction and financing (DLD legislation (opens in a new tab)).
Before you sign for an off-plan unit, check that the developer is on DLD’s list of licensed developers (opens in a new tab) and that the project is registered — DLD lets you track the status of projects on its website and in the Dubai REST app.
The buying process, step by step
Step 1: Agree your brief
Budget, preferred areas, property type, timing, and whether it’s a home or an investment. If you’ll need a mortgage, speak to lenders early.
Step 2: Shortlist with a licensed broker
Brokers in Dubai must be registered with the Real Estate Regulatory Agency (RERA) and hold a broker card. You can check licensed brokers (opens in a new tab) on DLD’s website, and property adverts carry a permit QR code (Madmoun) you can scan to see the listing’s approved details.
Step 3: Make an offer and sign the agreement
For a resale home, buyer and seller sign an agreement setting out the price, deposit and timeline. For off-plan, you sign a sale and purchase agreement with the developer.
Step 4: Pay the deposit and fees
The deposit is set in your agreement. The DLD registration fee is 4% of the price — see our guide to buying costs.
Step 5: Transfer and title deed
A ready property is transferred at a Real Estate Registration Trustee office, where the fees are paid and the registration is completed with DLD. Off-plan sales are registered by the developer, and the title deed is issued once the project is complete.
Step 6: Handover
Collect the keys, set up utilities and, if you’re renting the property out, plan how it will be managed.
What it costs
Budget for more than the price. The largest extra cost is the DLD registration fee of 4% of the property value, plus a trustee office fee (AED 4,000 + VAT for a property of AED 500,000 or more) and smaller title deed and administration charges. Buying with a mortgage adds 0.25% of the loan amount to register it. Our guide to buying costs breaks every item down with a worked example.
Visas linked to property
Owning property can support UAE residence. Property worth AED 2 million or more — one property or several — can qualify for the 10-year Golden Visa, including off-plan property bought from an approved developer (ICP (opens in a new tab)). DLD also describes a residence permit for owners of property worth more than AED 1 million. Read our Golden Visa guide for the details.
Tax: what Indian buyers should know
If you’re resident in India for tax purposes, the Income Tax Department requires you to report foreign assets — such as a Dubai property — and income from them in your return, in Schedules FA and FSI (Income Tax Department (opens in a new tab)). Non-residents and residents who are “not ordinarily resident” are treated differently.
Tax depends on your circumstances. We’re a real estate brokerage, not tax advisers, so please speak to a chartered accountant before you buy.
Questions buyers ask
- Can an Indian citizen buy property in Dubai?
- Yes. Foreign nationals, including Indian citizens, can own property in Dubai’s designated freehold areas, with the property registered in their name at the Dubai Land Department.
- How much money can I send from India to buy property in Dubai?
- Under the RBI’s Liberalised Remittance Scheme, each resident individual can send up to USD 250,000 per financial year, and buying property abroad is a permitted purpose. The limit includes your other LRS remittances that year, and family members can combine limits only as co-owners of the property.
- Do I need to be in Dubai to buy a property?
- Not necessarily. Non-resident buyers can use their passport for the transaction, and a legally valid power of attorney can represent you at the transfer. Many buyers still prefer to visit before choosing.
- Does buying property in Dubai give me a visa?
- Property worth AED 2 million or more can qualify for the 10-year Golden Visa, subject to the official conditions. DLD also describes a residence permit for owners of property worth more than AED 1 million.
- Can NRIs living in the UAE buy property in Dubai?
- Yes. The same freehold rules apply. UAE residents can also apply for mortgages from local banks, subject to each bank’s criteria.
Official sources
- Dubai Land Department — Frequently asked questions (opens in a new tab)
- Dubai Land Department — Registering a property sale (fees and documents) (opens in a new tab)
- Dubai Land Department — Dubai real estate legislation (Law No. 8 of 2007, escrow accounts) (opens in a new tab)
- Dubai Land Department — Licensed developers (opens in a new tab)
- Dubai Land Department — Licensed real estate brokers (opens in a new tab)
- Dubai Land Department — Madmoun QR codes on property adverts (opens in a new tab)
- Reserve Bank of India — Master Direction: Liberalised Remittance Scheme (opens in a new tab)
- Reserve Bank of India — Liberalised Remittance Scheme FAQs (opens in a new tab)
- Income Tax Department (India) — Reporting foreign assets (Schedule FA) (opens in a new tab)
- ICP — UAE Golden Residency guide (opens in a new tab)
This guide is general information, checked against the official sources above on 19 October 2026. It isn’t legal, tax or financial advice, and rules and fees can change — please confirm anything you rely on with the relevant authority or a qualified adviser.